
2026 Chevy Corvette Credit: GM
Transaction Prices and Monthly Loan Payments Reach Record Highs
KEY TAKEAWAYS
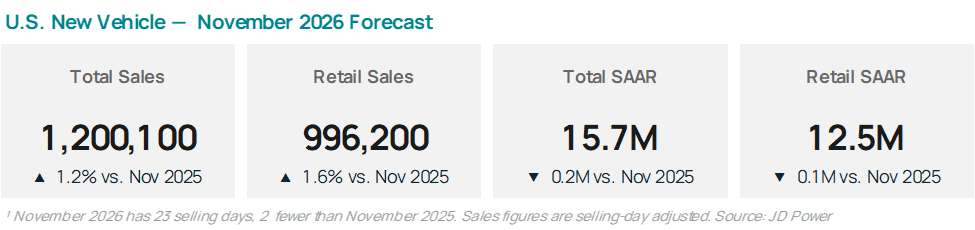
- November new-vehicle total sales on track for a 1.2% increase on a selling-day-adjusted basis
- Retail sales are on pace to rise 1.6% on a selling-day-adjusted basis
- Average transaction prices expected to rise 2.2% to a November record of $47,154
- Average monthly payments expected to rise 4.2% to a November record of $840
- Hybrid share of retail sales expected to reach 18.3%, up 3.0 percentage points, while EV share is tracking up 1.6 percentage points to 6.7%
The Total Sales Forecast
November 22, 2026 - Total new-vehicle sales for November 2026, including retail and non-retail transactions, are projected to reach 1,200,100, a 1.2% increase year over year, according to a joint forecast from JD Power and GlobalData. Reporting the same numbers without adjusting for the number of selling days translates to a decrease of 6.9% from November 2025. The seasonally adjusted annualized rate (SAAR) for total new-vehicle sales is expected to be 15.7 million units, down 0.2 million units from November 2025. November 2026 has 23 selling days, two fewer than November 2025.
The Retail Sales Forecast
New-vehicle retail sales for November 2026 are projected to reach 996,200, a 1.6% increase from November 2025. Reporting the same numbers without adjusting for the number of selling days translates to a decrease of 6.6% from November 2025. The SAAR for retail new-vehicle sales is expected to be 12.5 million units, down 0.1 million units from November 2025.
Thomas King, president of OEM solutions at JD Power:
“November results demonstrate the ongoing tension between vehicle affordability and sales volumes as the industry navigates elevated interest rates and fuel prices. Transaction prices are up 1.2% from October and 2.2% from a year ago, to a new record high of $47,154 for the month of November. Monthly finance payments are up 0.6% from October and 4.2% from a year ago for a November record of $840 per month. In contrast, retail sales are on pace to rise 1.6% on a selling-day-adjusted basis and decline 6.6% without the selling day adjustment.”
All these dynamics are playing out as inventory on dealer lots is increasing, albeit by a modest amount. Retailer inventory levels have increased 6.8% year over year to 2.4 million units.
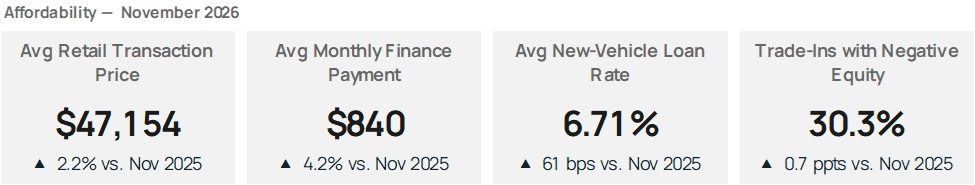
Compared with a year ago, the average interest rate on new vehicle loans is 6.71%, up 61 basis points and the highest November level since 2023.
More buyers are carrying negative equity on their trade-ins. In November, 30.3% of trade-ins are projected to have negative equity, up 0.7 percentage points from a year ago.
To manage monthly payments in the face of higher rates and negative equity, consumers are using longer loan terms. A total of 12.8% of new-vehicle loans are forecasted to have terms of 84 months or longer, up 1.1 percentage points year over year, helping to partially bridge the affordability gap.
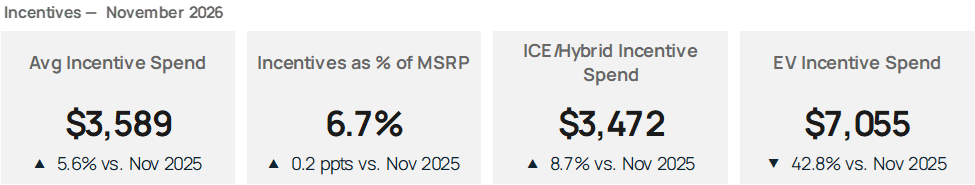
“To mitigate the affordability challenges, manufacturers are leaning into discounts to keep buyers in the market. Average incentive spending per vehicle is trending towards $3,589, a 5.6% increase from a year ago and $235 more than in October. Incentives as a percentage of manufacturer’s suggested retail price (MSRP) are expected to increase to 6.7%, up 0.2 percentage points from November 2025.
“The divergence in manufacturer incentive strategies by powertrain continues to be evident in November. Incentive spending on traditional internal combustion engine and hybrid vehicles is expected to increase $278 per unit year over year, up 8.7% to $3,472 in November 2026. Meanwhile, EV incentives moved in the opposite direction, with a forecasted decline of $5,287 per unit or 42.8% to $7,055, from an elevated base last November.
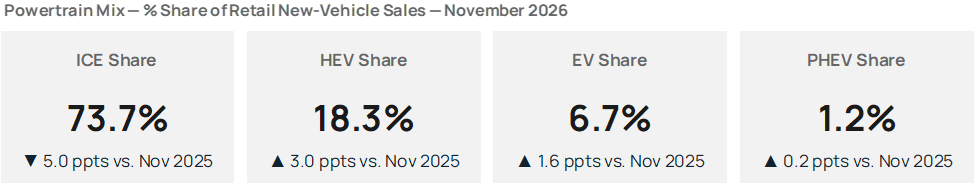
“Buyers continue to shift toward hybrids, with hybrid share of retail sales expected to reach 18.3%, up 3.0 percentage points from last year, due to elevated fuel prices and increased availability of hybrid vehicles. EV share is expected to be 6.7%, up 1.6 percentage points year over year, a return to growth following October’s decline, as the comparison now laps the lower base that followed the expiration of the federal EV tax credit.”
Global Sales Outlook
David Oakley, manager, Americas vehicle sales forecasts at GlobalData:
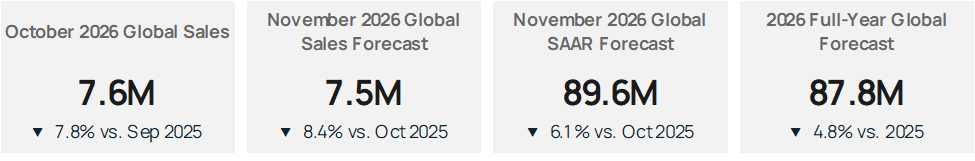
“October global light-vehicle sales are estimated to have declined 7.8% year over year to 7.6 million units. Once again, a sharp fall in sales in China—according to preliminary estimates—caused global sales to decrease year over year, whereas total global sales minus China were relatively stable. The global annualized selling rate for October was estimated at 89.1 million units, down from 89.3 million units in September.
“The Chinese market saw an estimated 27% year-over-year decrease in sales in October, excluding any vehicles intended for export. Along with a scaling back of government support via trade-in subsidies and EV tax incentives, higher energy prices are undermining attempts to boost consumer spending. While India has typically been a source of strength over recent months, its growth was likely less remarkable from a year-over-year perspective in October thanks in part to an extremely high base effect. A reduction in the goods and services tax (GST) in late September 2025 resulted in a surge in sales in October 2025. Still, the market is in a healthy state during the key festival selling season. Elsewhere, year-over-year gains in Western Europe were offset by declines in Eastern Europe, while South American sales were flat, and Japanese volumes were down by 4.4% year over year.
“November sales are expected to decline 8.4% from November 2025 to 7.5 million units. This would translate to a selling rate of 89.6 million units, down by 6.1% year over year. Many of the themes observed in October will likely be repeated in November. Chinese sales will decline year over year, while India may provide less support than it did in the earlier months of 2026. The Middle East is expected to continue seeing year-over-year losses due to the regional conflict and its consequences.
“Our forecast for total global sales in 2026 now stands at 87.8 million units, compared to 87.9 million units a month ago. This forecast would represent a 4.8% year-over-year decrease, with 2026 now looking certain for an annual fall at this late point in the year.”
About JD Power
JD Power is a proven leader in business-critical data and intelligence to drive auto-related decisions with confidence and clarity. By leveraging unmatched proprietary data, advanced analytics and deep industry expertise, JD Power fuels original equipment manufacturers, retailers, lenders, insurers and partners to enhance their performance.
Since 1968, JD Power has delivered incisive guidance and intelligence about customer interactions with brands and products. To learn more about the company’s business offerings, visit JDPower.com.
About GlobalData: https://www.globaldata.com/
Source: JD Power